Showing posts with label market direction. Show all posts

The Index, Market Tones, Trading Zones

The Malaysian markets last week would be a good subject matter for case study among all business students. Why is that when the index was above 1,350 and headed higher, that the general undertone of the markets was suspiciously muted.


Then the US markets had their biggest fall in months, and the local bourse fell in sympathy in the opening minutes but soon switched screens and started what I would term as the best "trading zone" this year.

Do all syndicates or big players act in concert? I don't know man, but it seems that there is a switch which most of them follow - as to who gets to push the switch, I don't want to guess too much.

The bulk of private investors have been waiting for this kind of "trading zone" - its a period where speculative and stocks with "stories or earnings upgrade" will move, and find good follow through as well. Usually this will last at least 2-4 weeks.


We cannot be looking at the main index to gauge sentiment as the index is too heavily weighted to big caps. The underlying tone of the markets has been set and I have mentioned before that the time is ripe for a run.

If you look at the privatisation of Measat and Tanjong, that could very well trigger a downtrend for the market but it didn't. Then we have the yet unresolved Kenmark situation which was followed by the bitter after-taste Mudajaya debacle - which could have also derailed investors' confidence. But no, the market was marking time.


When something is supposed to go down but does not, it usually will be up. You can infer the same from the above events.

The same is true, if something that is supposed to go up but doesn't, it will go down - these things never stay at parity. Important rule of thumb here. Remember the many times your friends or brokers telling you this stock or that stock will go up because of: new projects / earnings upgrade / owner playing the stock up / etc... if they do not go up, they usually will not stay still ... they will go down.


Enjoy people...

So What Has Changed?

The volatility is numb minding, or rather mind numbing. To summarise, its about debt. When we had the subprime mess, the governments everywhere could still print money and stimulate their economies. When it is sovereign debt, those countries cannot just print. The outstanding debt looks too large and no is willing to buy new bonds unless its issued at very high yields. Trouble is the countries affected are mainly inside the Eurozone. The Greeks, the Portuguese and even the Spaniards cannot issue new debt in their own currency, they only have the Euro. You cannot be issuing in Euro as you have no way of controlling your monetary policies that is set by the ECB.

http://malay.cri.cn/mmsource/images/2010/04/13/3e94588daec54377a37bb5ae58ab4b9d.jpg

If they were still in their own currency, they still can devalue their currency, which is now no longer an option. The whole hoopla was due to rumours that the Chinese were about to sell their Euro bonds holdings. Now that they have denied it, the markets all rallied, but WHAT HAS CHANGED??? Nothing!!!

The entire scenario would have to see the Euro being depressed for quite some time. Though the EMU have stepped in aggressively, Greece is not the only one playing truant. Portugal and Spain, and maybe Italy will be the "me too" category. You cannot help one without helping the others. The more they help, the more downward pressure on the Euro. I can see the Euro going down to 1.1 to the dollar with fears of parity even by year end.

The entire scenario will cub the recovery process globally as the coming theme hitting the markets will be how the EU will have a lot less purchasing power, hence exporting countries to the EU will see a dismal scene playing out.

http://i.i.com.com/cnwk.1d/i/tim//2010/02/19/fmimg3166975204828791556.jpg

Some may take it that Asian and Latam may be hit as collateral damage, but I think the investors will actually pour more funds into the US and emerging markets as they will be the only bright sparks. The saving grace for the past 12 months have been that emerging markets have been relying a lot more on domestic demand and trading among themselves, and that underpinning would be sufficient to pull them back up.

But not yet, lets wait till the World Cup is over people, no rush.

Getting A Hold On Market Weakness

Now that the US markets have been down 3 straight days, I get a lot more queries on "what the hell is happening" ... "is this going to continue" ... Well, first of all, in my lifetime, I have never seen a major correction whilst interest rates are near all time lows, have you??!! We are so used to a robust equity market for the last 12 months, that we lose sight what is a normal dip.

The trouble is exacerbated when fundamentals cannot explain these 3 days of weakness, we go searching for reasons, and usually they are the wrong ones. Some will cite that Obama's health care plan faces a setback with a Republican taking over the late Ted Kennedy's seat... some will say its Obama's thinking of implementing a tax on "traders or firms taking prop positions" ...

The whole thing is further exacerbated by people looking to charts and technicals to explain the situation - this is the best part, when all other reasoning fails, let's look at charts ... well you might as well consult a fengshui master. Charts are not so bad really, they are tools which can help us.

I came across a pretty straight forward guy looking at technicals of emerging markets, pretty OK.
-------------------
Richard Shaw is the managing principal of QVM Group LLC, a fee-based investment advisor based in Connecticut. QVM manages portfolios uniquely designed for each client on a flat fee basis through the client’s own accounts at Schwab, Fidelity or Vanguard.

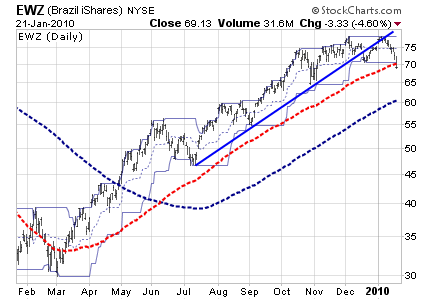
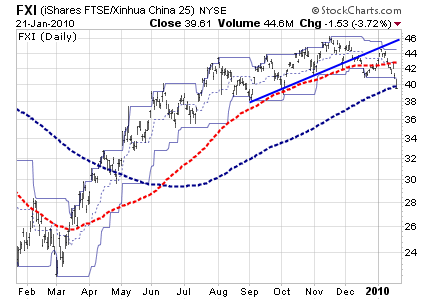
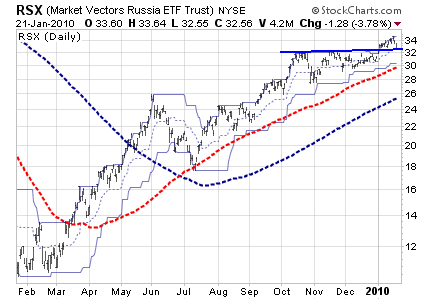
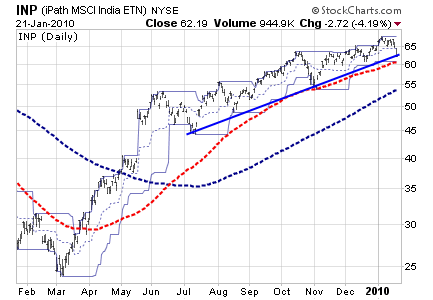
The BRIC countries are a mixed story. Brazil and China have clearly broken support, while Russia and India are still in rising patterns. Brazil may be a Sell. We think China is a Sell. Brazil has broken three conceptual support levels — its trend line connecting recent bottoms, its 21-day lower price channel and its 100-day moving average (in red). The 200-day average (in blue) is about 15% away.

ewz1

As of January 21, China has broken four of four conceptual support levels, including its 200-day moving average, which is generally held to be a major significance.

fxi

Russia is in a rising pattern, but is testing a support level created by two recent highs that had formerly provided resistance. That support level is above the price channel and moving average support levels.

rsx1

India is still in a rising pattern, but is close to a level where three conceptual supports converge (trend line, lower 21-day price channel and 100-day moving average).

inp

The other countries within the emerging markets index are also a mixed bag.

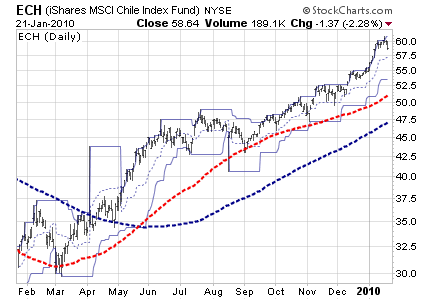
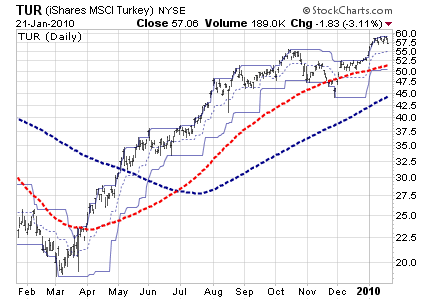
Chile and Turkey are the two with the strongest current price patterns.

ech

tur

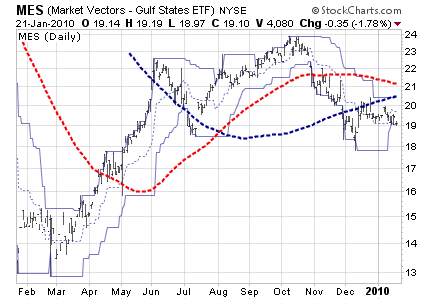
The Middle East has the weakest price pattern.

mes

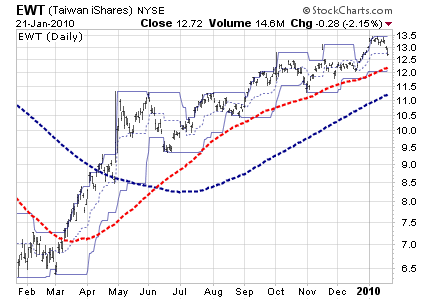
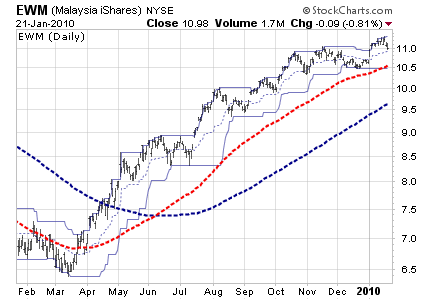
Taiwan and Malaysia are in OK price chart conditions.

ewt

ewm1

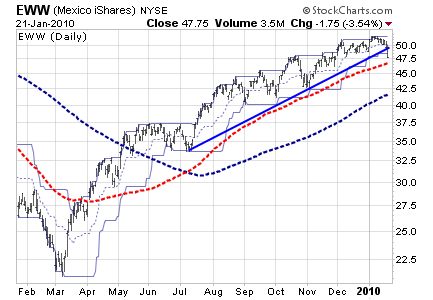
Mexico is still in a rising pattern, but has pierced its bottom connecting trend line and its 21-day lower price channel. The 100-day moving average is not far away.

eww2

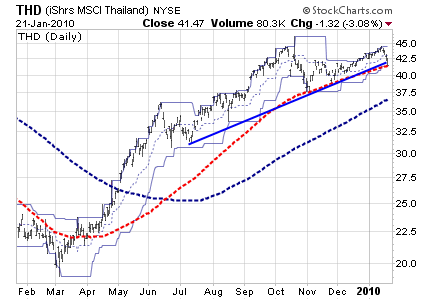
Thailand did not exceed its high achieved in October and is now at critical support formed by the convergence of its trend line connecting bottoms, its 21-day price channel and its 100-day moving average.

thd1

--------------
My concluding view is that we are just in an adjustment mode, I do think the markets will resume its bullishness very soon. I also see some markets drifting away from each other as the domestic liquidity conditions and monetary policies are diverting. Many are trying to rein in excessive lending and excessive property price speculation. I do think Malaysia is less affected by these issues. You should also read the recent posting on PEG ratios to get a better view that not all markets are similar, we are all going up using different routes.

Market Commentary


Just looking at the markets today, some may not know what to make of it. Its like uncertain and the energy is misplaced and incoherent. Looking at the leaders board, Konsort has raced up the volume list, the stock that links it up is Pelikan. They have a mutual substantial shareholder, look it up. There are talks that Pelikan is being planned for a MBO or a private equity buyout (part of the reason why I highlighted it as a buy below RM1.00). Both should be OK for a swift trade. Not encouraged, only for smart and savvy traders who can move in and out quick by looking at volume and trends.

The other thing one can surmise from the gainers is that the realignment caused by the "new" FTSE-KLCI 30 index, which I have highlighted as "very important". The adjustment process favours certain stocks which takes out some of their free float capacity. Hence look for firm support for Tanjong and Commerce.

Some strategic accumulation can be seen in IOI Corp, which looks to me to be a good base building level, or some "substantial shareholder" thinking that this is the "right levels" to accumulate strongly.
Fergetabout UEM Land or Tebrau, never liked their run up as the story is still wishy washy. No follow through, corporate plans all habuk, tarak api punya. I don't like many stocks now as I think markets do look tired, but if you point a gun to my head to force me to buy one stock to hold till rest of they year, I would probably say E&O.


p/s photos: Elanne Kong & Janice Man


Can Asian Markets Continue To Outperform The Rest - Revisited


Asian equity markets have outperformed mature markets in 2009 thanks to continuous foreign institutional investor (FII) inflows amid diminishing risk-aversion among global investors and some signs of green shoots in Asia. As of July 8 2009, MSCI Asia Pacific gained 11.6% ytd with China and Sri Lanka as the best performers, and Australia and New Zealand as the worst performers. Despite impressive improvements, downside risks remain due to bleak corporate earnings outlook, worries over the real economy and revival of any global risk aversion.

Trends
# 2009 MSCI Asia Pacific performance in USD terms: 11.6% ytd as of July 8, up 38.7% during March 2-July 8
# 2009 MSCI Asia performance in USD terms: 11.3% ytd as of July 8, up 38.0% during March 2-July 8
# 2009 MSCI Asia (ex Japan) performance in USD terms: 29.8% ytd as of July 8, up 57.1% during March 2-July 8
# Best performers (ytd as of July 8, 2009): China: 71.5% | Sri Lanka: 56.2% | Indonesia: 53.8% | Taiwan: 47.0% | India: 42.6% | Viet Nam: 41.4%
# Worst performers (ytd as of July 8, 2009): the Philippines: 30.1% | Singapore: 31.0% | Thailand: 29.3% | South Korea: 27.3% | Pakistan: 26.7% | Hong Kong: 23.7% | Malaysia: 21.6% | Japan: 4.9% | Australia: 1.1% | New Zealand: 1.0%
# In 2009: Asia's equity market (ex Japan) have outperformed mature markets, up 29.8% ytd as of July 8 2009, while the S&P 500 Index and the U.S. Dow Jones Industrial Average fell 5.6% and 9.5% respectively during the same period. Continuous FII inflows to Asian equity markets have taken net flows to a positive US$14.4 billion as of June 24 2009, significantly up from US$10.8 billion in H1 and US$9.6 billion in H2 2008.
# Since March 2009, Asian equity markets have witnessed a rally following a surge in U.S. markets and began to benefit from the widening valuation gap on the back of relatively resilient macroeconomic fundamentals. During the March 2- July 8 period, MSCI Asia (ex Japan) rose by 57.1%, significantly higher than the S&P 500 Index and the Dow Jones Industrial Average which gained 25.5% and 20.9% respectively.
# Valuations: Taiwanese shares are the most expensive in the region, 64.6 times reported earnings, followed by New Zealand (38.0x), China (33.1x for A-shares) and South Korea (32.1x). On the other hand, Singapore (12.1x) and Pakistan (9.7x) are cheapest when compared to their regional peers.
# 2008 Review: The peak-to-trough decline in Asian equities in 2008 (more than 70% for some markets) surpassed the 60% fall in local currency terms during the 1998 Asian financial crisis. Sustained outflows from offshore Asian funds took total net redemptions in Jan-Oct 2008 to a record high such that all money that flowed in during 2007 flowed out.
# Market Integration: There is a noticeable upward trend in the Asia-U.S. correlation with the correlation parameter picking up sharply in H2 2008 (peaking during mid-Oct 2008). However, average correlations for emerging Asian equity markets are generally higher between the region's markets than with U.S. markets.
# Government intervention: Several countries including Taiwan, Pakistan, Vietnam, Thailand intervened in the stock market by narrowing the trading band, introducing stabilization fund to contain volatility, banning short-selling, directing government funds to buy share.

Outlook
# Upsides: AXJ region is now attractively valued, and buying into most of the region's equity markets seems a better bet than bonds amid increasing bond issuance. Also, as of end April 2009, market capitalization of Asian Pacific markets ($10.2tn) has come ahead of that of European markets ($9.3tn, including Africa and the Middle East) as Asian stock prices sour at a faster pace than European ones.
# Downsides: Goomy earnings forecasts, worries over the U.S. economy, exit by local investors and also FIIs alarmed at greater than expected impact of global slowdown on Asia's growth, exports, fiscal deficits, slowing consumer spending and investment may have negative impacts. Investors may move money to bond markets from equity markets in an anticipation of slower global economy's recovery due to the spread of swine flu. High (external) debt exposure of corporate sector in some countries and risks of real estate correction and bank profitability are additional risks.
# Given decreasing inflationary pressures and relatively healthy fiscal positions, further fiscal and monetary stimulus policies by Asian governments will able to boost the region's equity markets in H2 2009.
# Prospects for further inflows into Asian equities remain substantial, as global portfolio continue to adjust from relatively underweight positions, and given cheap equity valuations relative to bonds.
# Asian stocks have yet to reflect expectations for a powerful, synchronized recovery in the global economy as markets are still bearish on global growth and on emerging markets growth.
# Markets would likely grind higher first, before dropping by 20-30%: Catalysts for a correction are (1) flattening improvements in second derivatives; (2) softer than expected data coming out of China and; (3) a US% rally, which takes liquidity out of Asia ex.
# The recent rally in Asian equity markets might not continue due to still-weak real economic condition in many countries and the region's ultimate reliance on exports to the U.S. and EU, which means that financial-investor sentiment will remain susceptible to economic setbacks in those markets.


p/s photos: Meisa Kuroki

Where Are We In This Stock Market Rebound? - Deflation Or Reflation Trades


The key historical lesson from past U.S. recessions and severe bear markets is that the stock market tends to bottom out three to six months before the economic contraction reaches its maximum. From the recent economic figures, it is plausible that the U.S. stock market is possibly at a stage where the recession is passing its worst phase. If history is any guide, the stock market should have entered a bottoming process a few weeks back.

Cyclically-sensitive sectors and markets have outperformed as shown in my recent posts, which further signals that reflation trades could soon make a comeback. For instance, emerging markets have continued to outperform the global average. Early cyclicals, such as consumer discretionary and technology sectors, are also beginning to outperform the broad benchmark
equity index.

Finally, it seems that some segments of global financial markets are repositioning themselves for reflation trades. Commodity currencies have experienced a sharp rebound in tandem with the broad commodity price index as well as the crude oil market. In recent history, these moves have been a harbinger of a more broad-based return of the reflation trades.

The key point here is that the decline in stock prices has been the worst since the Great Depression, and has gone a long way to discounting a severe economic recession and financial fallout. Of course, at previous major bear market lows, valuations have been much better than today’s level so it is open to debate whether the worst is discounted – but we should not ignore that reflation this time around is much bigger than ever before, so P/E multiples may not need to go significantly lower than where they stand today. Monetary authorities and governments around the world are getting increasingly aggressive in combating the financial and economic hurricane, all of which means that deflation trades are very late.

The risk-reward tradeoff suggests that going forward, deflation trades are unlikely to reward investors and they should raise their exposure to stocks at the expense of bonds. All that points to a more stable market DESPITE the recent run up. It looks more solid than what I thought it was a few weeks back. A few weeks back, I tended to think it was a bull run with a chance for a 10% correction. But I have shied away from that conclusion, I do think there will be bouts of soft selling which will then attract fresh funds to reposition before launching up the next level. I see the Dow testing 9,300 sometime this year and holding. For KLCI I think 1,140 is possible.


p/s photos: Zhang Xin Yu

Where Are We In This Financial Crisis & Recovery?


Where are we in the global crisis? Are we recovering yet? Why are stock prices rushing upwards when the real economy still looked unsettled? I have tried to convey some answers in my posts before. Let's look at some more related factors:

a) economic statistics - no doubt the stats that have been coming out are still bad, but we have to remember that economic stats are dated, things that are dated means we all should know already, they do not tell us something we don't already know, we went through it, we read about how many companies have been downsizing, we read about plunging commodity price and the Baltic Dry Index, we hear about the number of foreclosed homes ... hence the main aim when looking at economic stats now is to look for signs of recovery, then we have to distinguish between year on year, quarter on quarter and month on month data, year on year is the hardest to calibrate - we already know that things will be very bad on a yoy basis, thus we look at comparative yoy figure for the past few months, yoy figures are important in that it takes out seasonal effects - its the same month as last year, month on month is deceptive because of seasonal effects e.g. figures for February (Chinese New Year effect / holidays / front loading) when compared to March will have the seasonal effect, which is why it is safer to look at quarter on quarter as it would indicate a more genuine trend change ... considering where we are in the recession cycle, everyone should be looking at the rate of decline, or rather the changes to the rate of decline to get at hints of recovery

b) bad news discounted - just how much of the bad news has been discounted, we can only guess, but when you take into consideration the spike in risk aversion over the last 7 months (which can be measured), it is reasonable to assume that prices have more than discounted the bad news because a depletion of confidence and a spike in risk aversion will lead to oversold markets, and thats where we are coming back from, an oversold position

c) bear market rally - in the beginning I would call it a bear market rally, but since February I think its a cyclical market rally, many who call this a bear market rally are those who totally missed out profiting from the rally, the more it rallies, the louder will those who did not buy will shout that it is a bear market rally ... you will also notice that those fundamentals driven experts have gone a lot quieter in recent weeks as the markets continued to climb because they have been wrong and wrong week in week out, hence the only people still shouting are technical analysts, or rather those chartists who also failed to spot the rising trend are now calling for a massive correction ... nobody wants to be wrong and at the same time not being able to make some money when others have traded profitably, beware of the underlying reasons why some people are saying certain things

d) what could go wrong - markets will seize up again if there are major unknowns appearing again, such as if a few big banks were to collapse, or that some of them would require another bailout in the hundreds of billions again, that is not likely after the "stress test" that did not please many people, to me its a very good move by Geithner because it opens up the books and sores for all to see, only with another round of panic will the bond markets seize up, and when they do, the risk aversion will return, looking at what has transpired, that risk has be lowered significantly

So, yes, foreclosures will be bad, unemployment may still rise ( I expect them to peak by end of June/July 2009), pockets of Europe will still be very bad, but the focus has shifted to investors looking for signs of recovery, and every time economic stats DOES NOT say that, markets will just drift lower, but not correct massively, as the amount of liquidity and the need to have an exposure in order not to miss out, will counterbalance the markets in the weeks and months ahead.


p/s photo: Jessie Chiang

No Correction Till 10,000 For The Dow??!!


This was easily one of the better written articles on the markets that I have read for the past couple of weeks. Its by Andrew Butter, and he basically argued that there would be no correction until the Dow reaches 10,000. Its pretty much in line with my views that I have.

Andrew Butter: At Davos, Professor Nouriel Roubini declared that US banks were insolvent. On 14th March he declared that the incipient US stock market rally was a "dead-cat-bounce-..." that would be overturned by the terrible economic prospects.

Last time I looked, the Dow was up almost 30% on 9th March, which puts it well out of normal dead-cat-bounce territory.

And "Hallelujah", the Stress Tests have confirmed "beyond any reasonable doubt" that Secretary Paulson was absolutely correct when he announced to an adoring public in July 2008 that "the US banking system is safe and sound".

Well actually, as Lord Cooper's aide used to say in Evelyn Waugh's classic "Scoop", "Up to a point!"

The "doomsayers", (and there are many) point to (a) P/E ratios (going down to 4,000) (b) the lousy economic prospects, (c) insider selling, (d) the still stinking banking system, (e) creative accounting, and... (Phew!)...(f) corruption and crass incompetence in high places, (and they say this HAS to have an unhappy ending).

I don't have an argument with most of that, except perhaps the "answer"; I'm not so sure that there will be an unhappy ending...haven't we had enough of those for one crash?

Perhaps there is a limit to how much damage you can do to an economy, even if you try real hard - look at Somalia, a failed state. But the Wall Street Bankers can only sit in silent admiration and marvel at how creative young entrepreneurs have figured out bold new ways to rip people off (of course that's just a cottage industry compared to Wall Street - what they need is some organization and a few lobbyists and then do an IPO).

Anyway, as it floated higher the rally got incrementally downgraded to a "sucker" then a "bear" then what...a "chump"?

Now there is apparently a legion of investors scratching their heads and holding their breath, waiting in strained anticipation for the next thing they don't understand to bite them in the backside.

But Professor Roubini is always right...RIGHT!

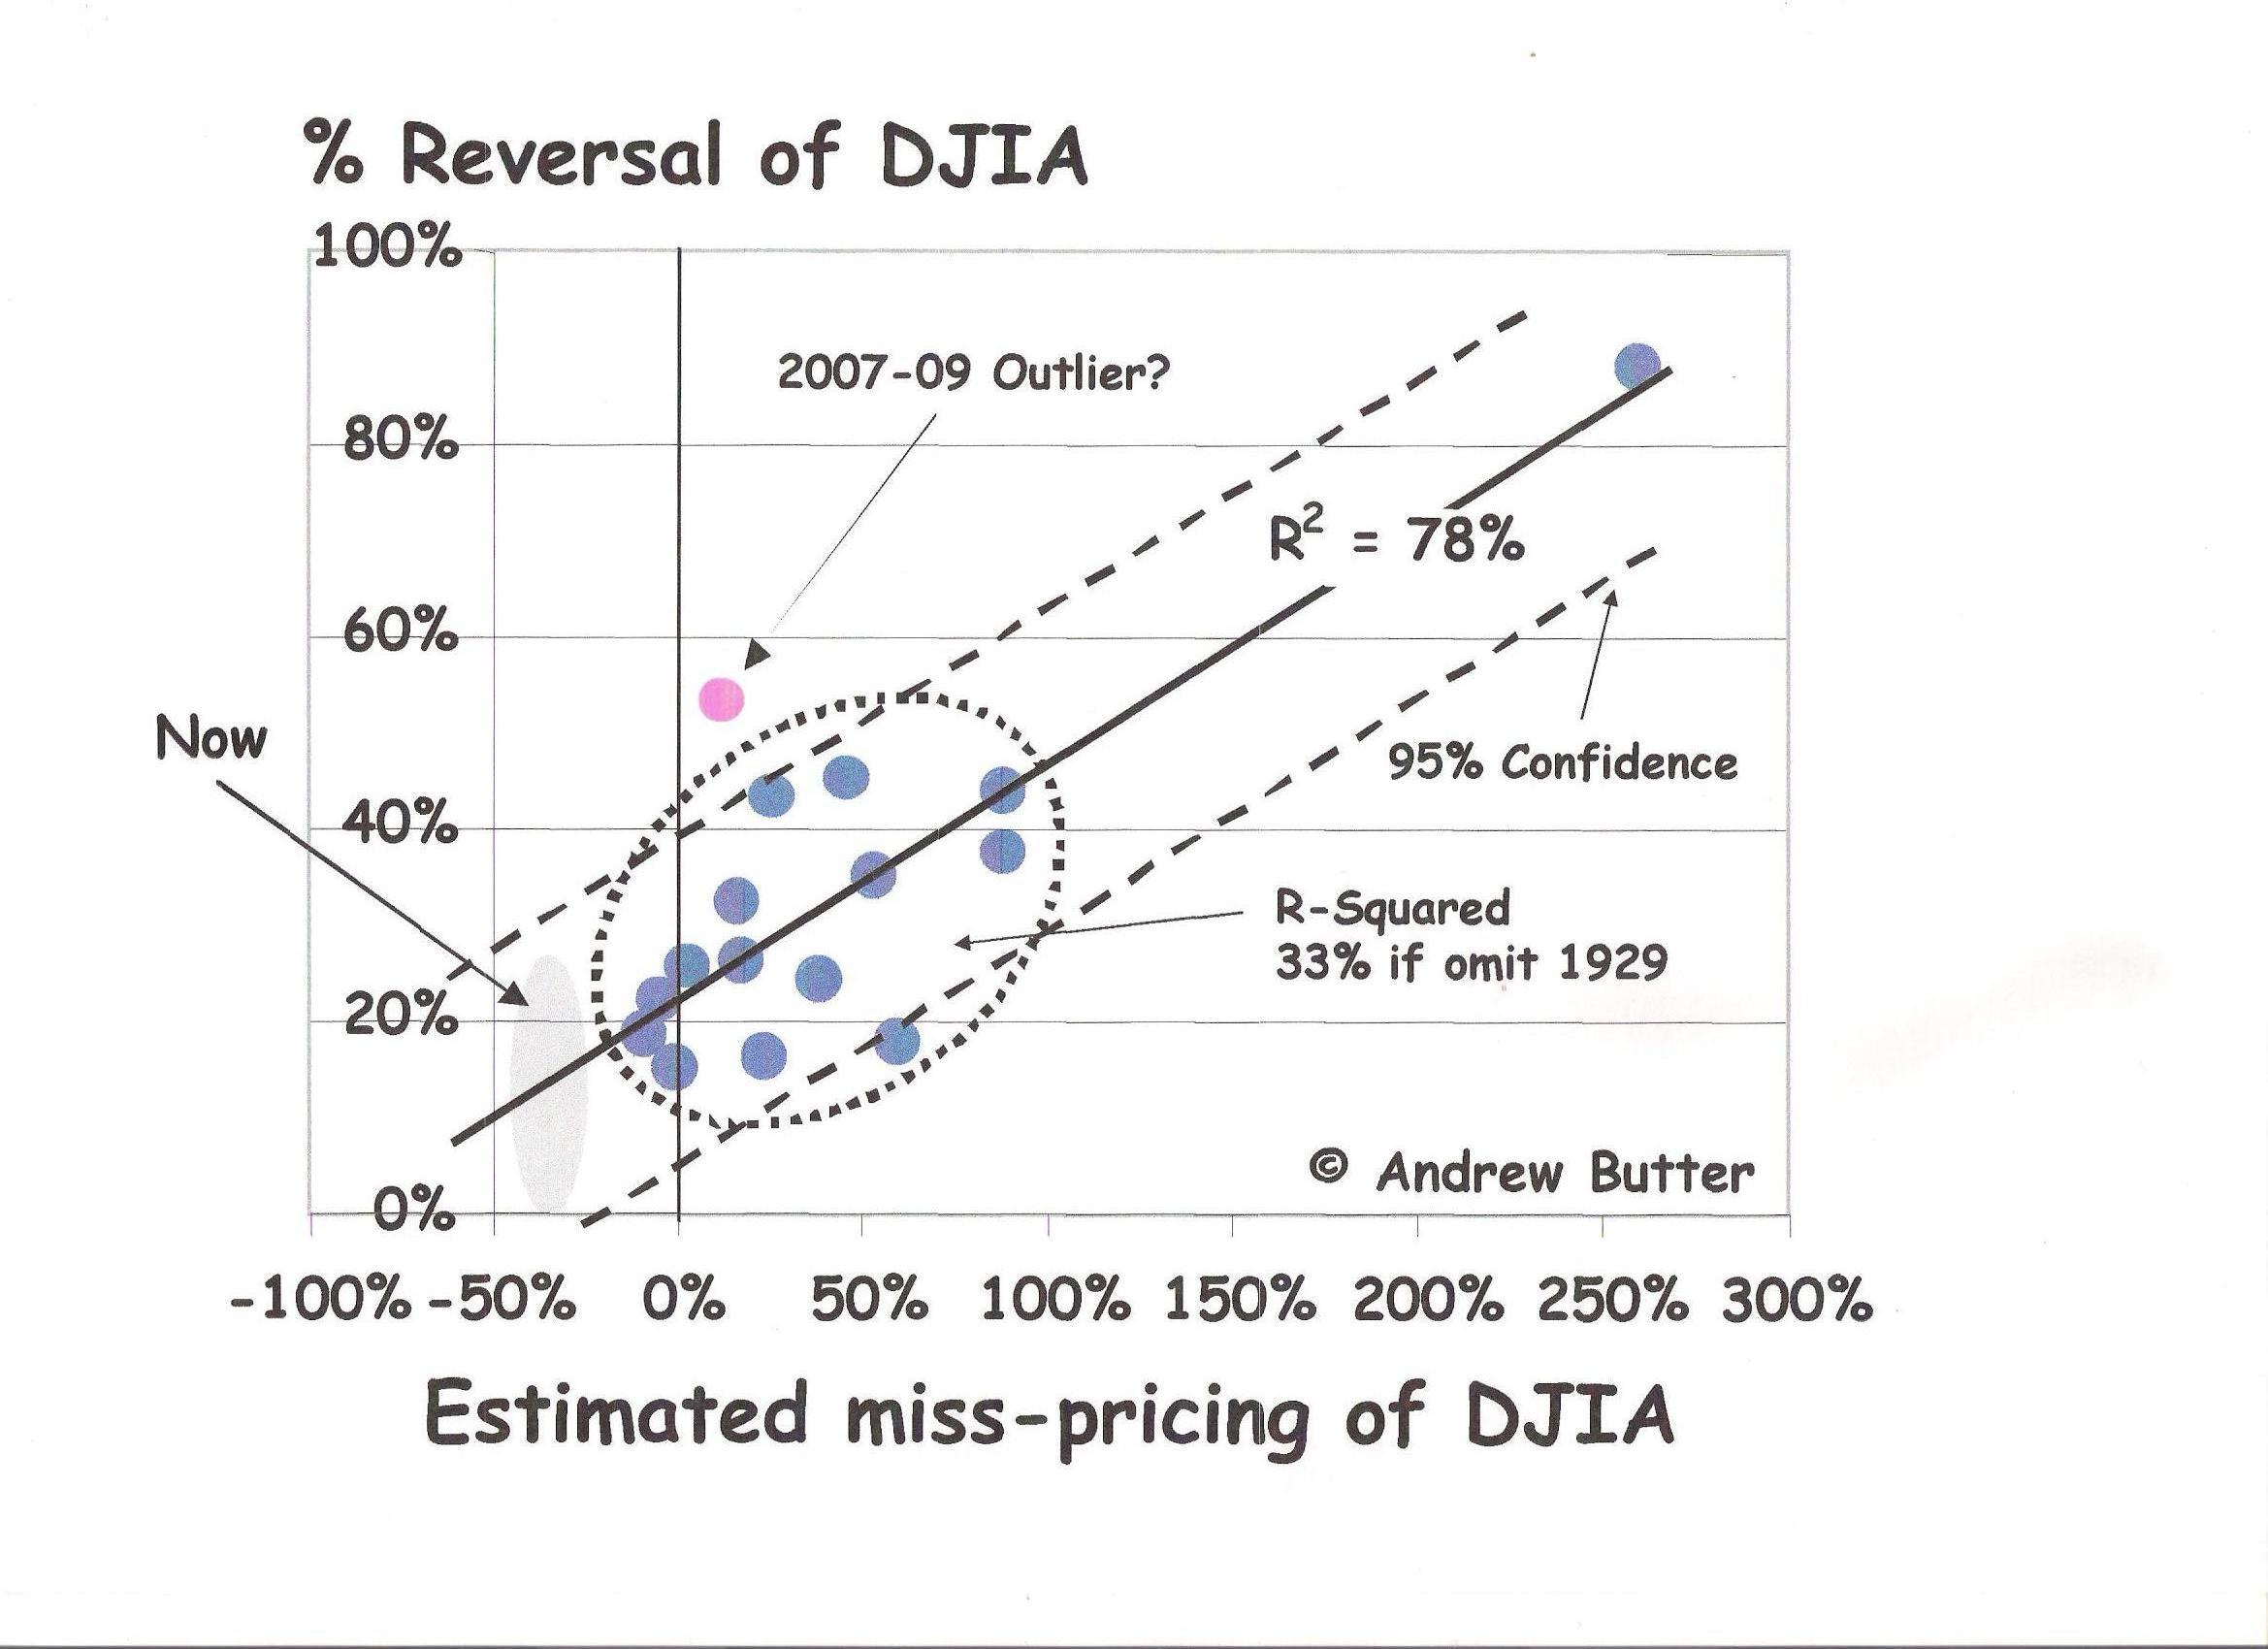
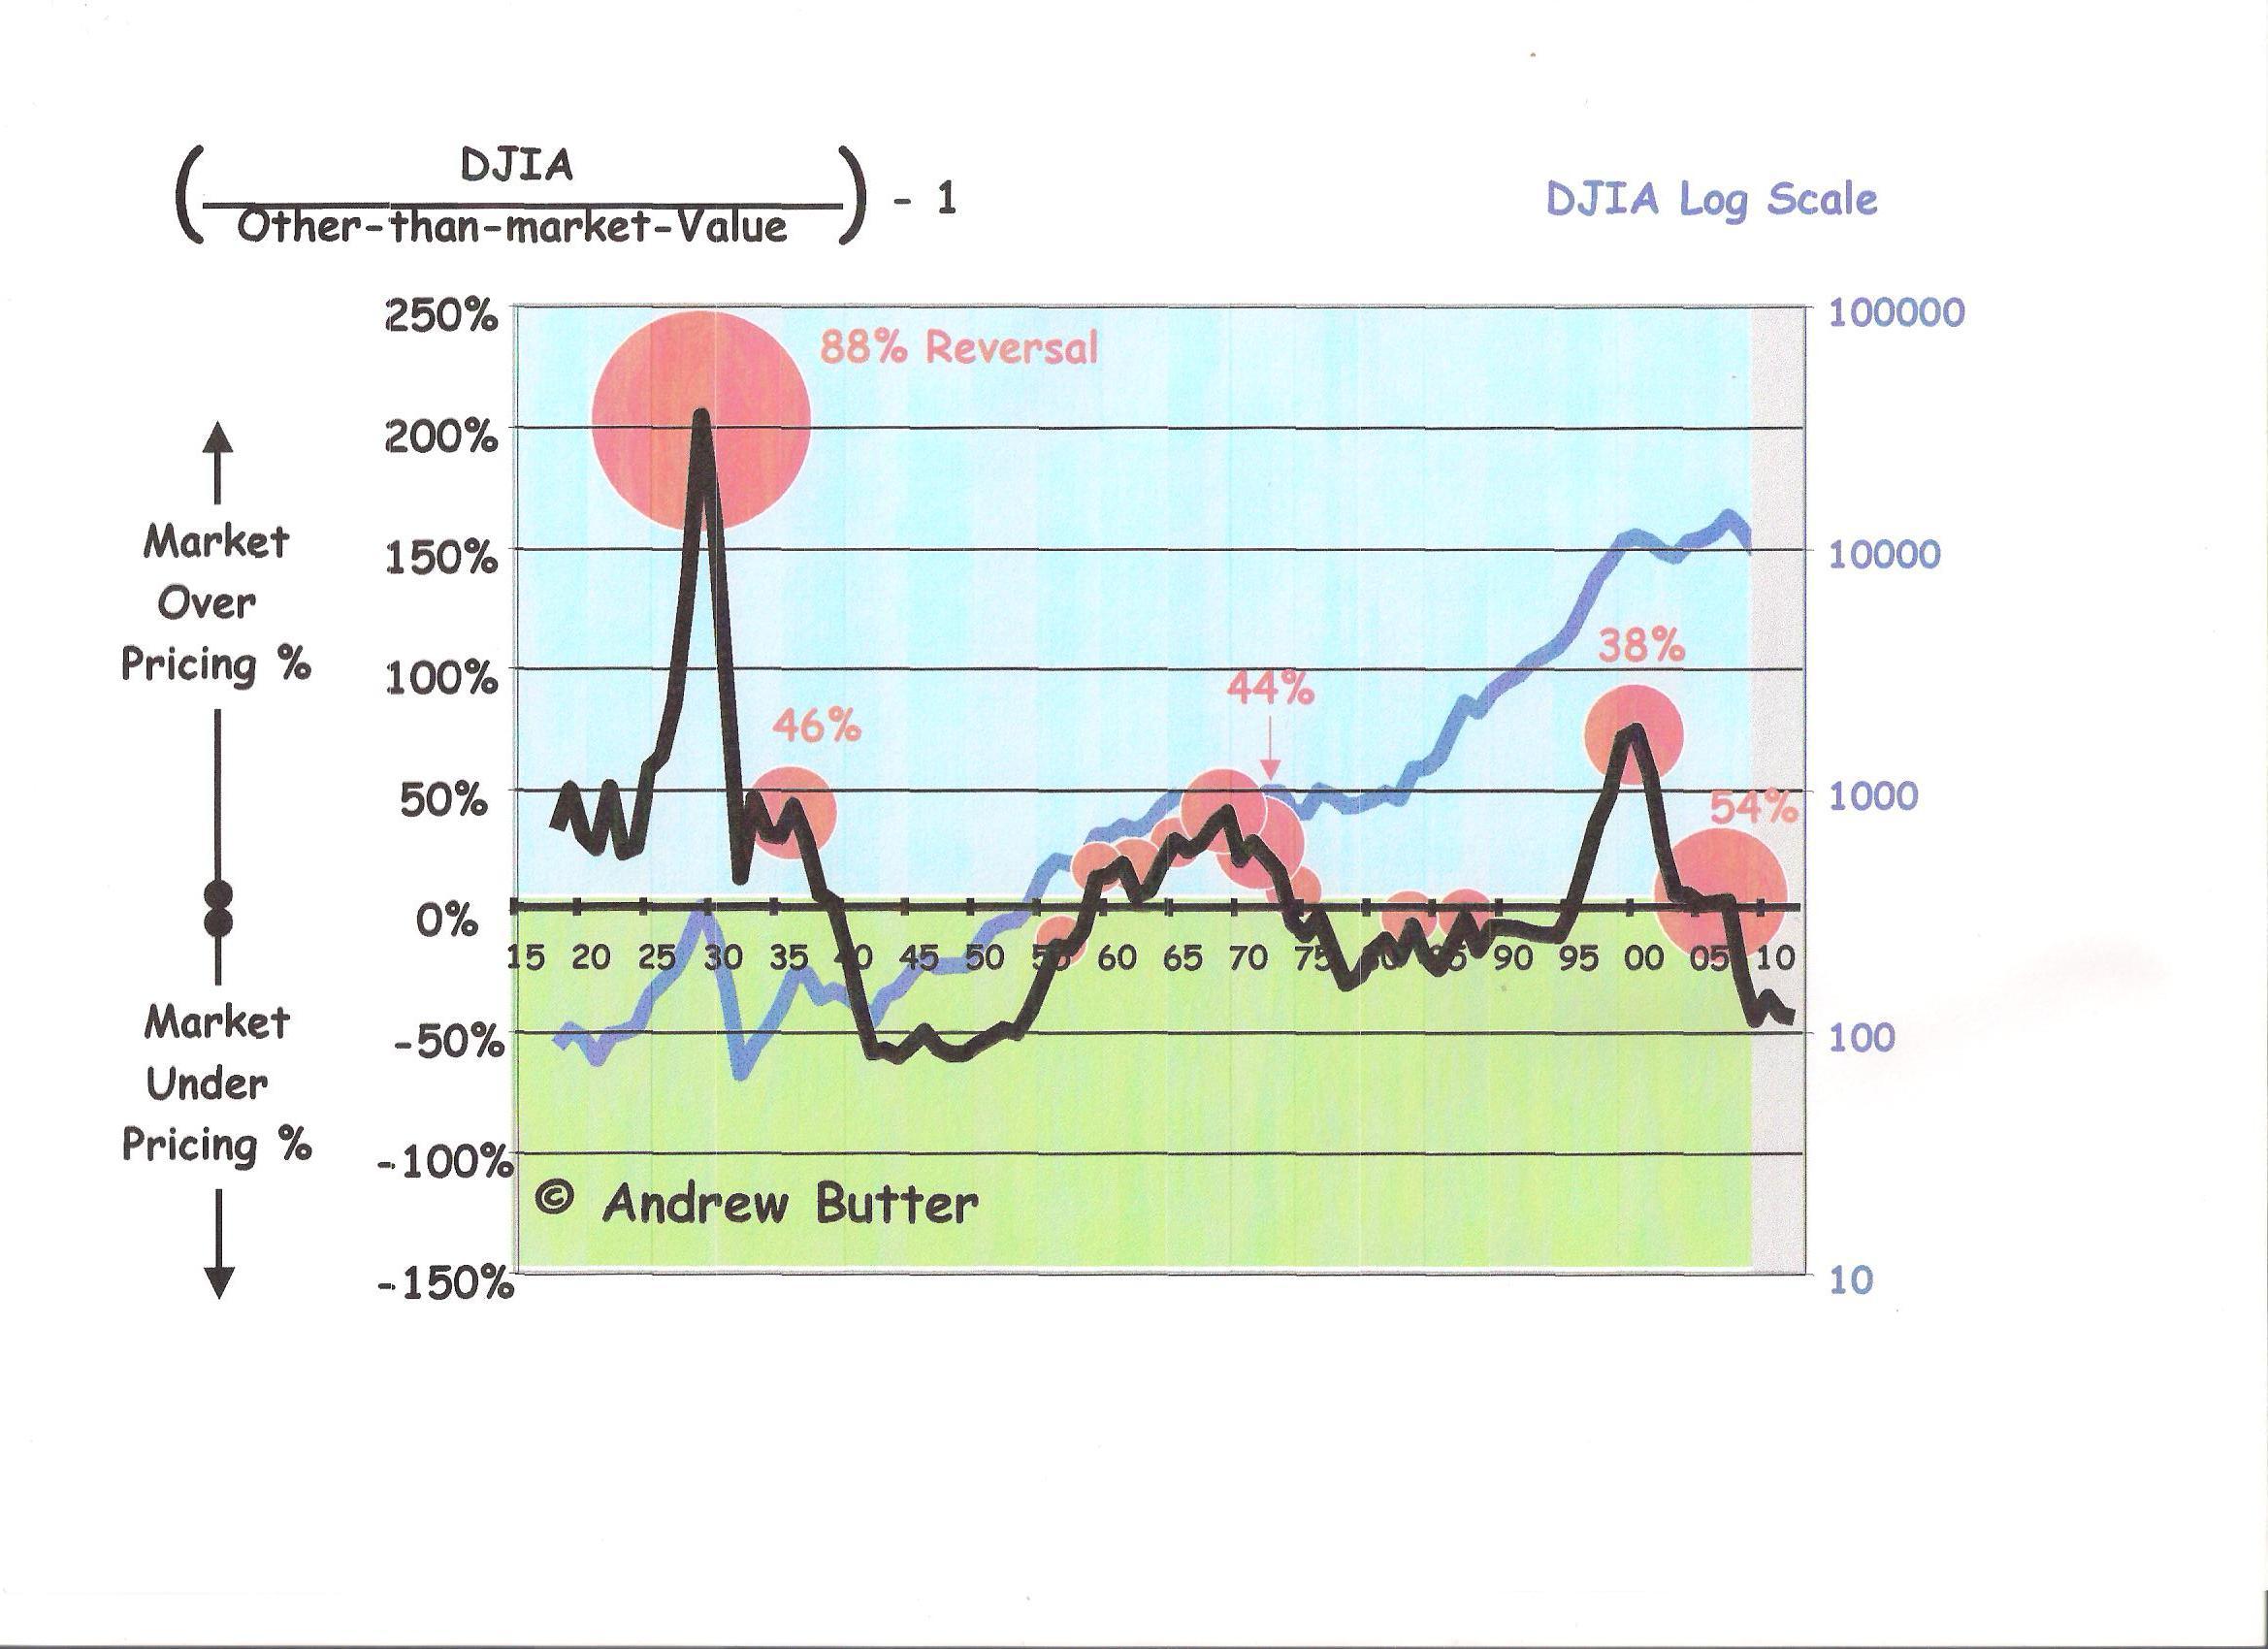
Well, up to a point. This chart compares the size of reversals over 15% for the DJIA since 1929 with the extent of mis-pricing (mis-pricing is explained here).

click to enlarge

So for that limited amount of data the extent of mis-pricing appears to be a reasonable predictor of the size of the reversal (I treated the recent reversal as part of the Dot.com reversal, i.e. as an outlier - I don't regard deliberately shooting yourself in the foot as a typical "market" phenomena).

However if the 88% reversal from 1929 to the eventual bottom three years later is taken out there is not a good predictor relationship (33% R-Squared is about random; although there is a range - only 5% chance of being outside the dotted line).

Anyway, market-long-wave analysis says that for DJIA breaking 10,000 in 2009 it will be 37% to 42% mis-priced (below); and that's for worst case nominal economic growth of minus 4% in 2009 and let's say worst case the 10 Year Note goes up to 4.5% from now (as the men in suits with their hands deep in the US taxpayers pockets try and raise more trillions - I won't discuss what they are holding in those hands).

And the downswing predicted from the previous upswing is 42%, so that looks about the bottom in mis-pricing on the downside to me.

Looking at the chart, it appears there has never been a major reversal of the DJIA (i.e. greater than 15%) when the mis-pricing was more than 10% (under), so regardless of the impeccable logic for why this was a sucker-dead-cat, I just don't see a reversal coming any time soon.

Looking at that another way, the extent of reversal compared to the history with the diameter of the rings sized to represent the extent of reversal:

This chart illustrates that reversals typically seem to happen when the market is mis-priced above the estimated "other-than-market", which intuitively makes a lot of sense.

Also, the size of the reversal appears to be broadly proportional to the speed at which the market went out of equilibrium and over 45 years when the market was mis-priced under.

Only three reversals happened when mis-pricing was negative and in each case the line was moving up towards zero, minimum was 10% mis-priced. That compares to twelve major reversals in the 45 years it was mis-priced over.

So right now, if indeed the Dow is about 40% mis-priced under, for it to be 10% mis-priced it will have to reach 14,000 this year which would be a bit of a stretch (history suggests it's going to bumble along in the range -30% to -45% for the next year at least).

So where does this leave the sucker-dead-cat-bounce rally, downgraded to a chump-rally?

My view from looking at that data, and assuming that the bankers are not going to manage to screw things up in 2009 as badly as they did in 2003 to 2007 (i.e. "no more surprises or super con tricks this rip-off-and-run season"), then it's highly unlikely that there will be a significant (more than 15%) reversal in the DJIA (and the S&P 500 correlates with that), certainly not worth breaking into a sweat over until the DJIA goes through 10,000.

If there is, well, I'll ring the neck of this darn cat that's been sitting on my lap since early March and barbeque it.


p/s photo: Zhou Wei Tong


Highest Percentage Of Stocks Above 50 Day M.A. Since Mid-2006


The highly respected folks at Bespoke Investment Group has further evidence confirming the current market rally. It will take a lot to derail the current uptrend. According to the people at Bespoke Research, as the market continues to rally, the percentage of companies now trading above their 50-day moving averages also continues to rise. As shown below, 92% of the stocks in the S&P 500 are now trading above their 50-days. This is by far the highest reading since mid-2006, and it is indicative of extremely strong market breadth.

Spx50day505

Every sector except Health Care and Consumer Staples has a >50-DMA reading of more than 90%. The Consumer Staples sector is at 88%, and Health Care is at 75%. Telecom only has 9 stocks in the sector, and all of them are trading above their 50-days. The Industrials sector ranks second at 98%, followed by Energy and Utilities at 97%. While still high, Financials and Consumer Discretionary have actually seen a decline in the percentage of stocks above their 50-days over the last week. The indicator maxes out at 100%, so there isn't currently much upside room from a breadth perspective. A pullback in these extraordinary numbers would be neither surprising nor unhealthy.

Finlindu505

Inftenrs505

Condcons505

Hlthmatr505

Utiltels505


p/s photos: Deepika Padukone


Many Sectors Moving Above Its 200-Day M.A.


Here is more comforting information that the US bull run may not be over so soon. Many analysts consider a stock moving above its 200-DMA to be a buy signal. Furthermore, it is also said that a bull market can be defined as one where major market averages are trending up above their 200-DMA. Through most of this bear market, we haven't seen many stocks or ETFs anywhere close to their 200-DMA. Now, that seems to be changing.

Thanks to the advent of ETFs in the US, it is easier to track movements in sectors. The sector ETFs are composed of many stocks, and that lends more credibility to the moving averages. There are a number of sector ETFs as well as the NASDAQ 100 have moved above their 200-DMA recently.
  • Technology iShares
  • Network iShares
  • Semiconductor iShares
  • Consumer Discretionary iShares

In addition, the NASDAQ Composite is a hair away from crossing over its 200-DMA and the Telecom iShares. Materials and Industrials ETFs are also only a few points away their 200-DMA. Looking farther afield, the iShares FTSE/Xinhua China ETF crossed above and now seems to be consolidating at a level above its 200-DMA. Other major market averages such as the Russell 2000 are only a few points away from their 200-DMA. Will they be rejected or will they power through and confirm something stronger than a bear market rally is underway?

How To Interpret Market Commentary & Analysis


We all get to read market analysis and commentary on a daily basis. These are information which will help us assess the pulse of the markets. As in anything, the ability to distinguish useless information from critical information is vital in helping us improve on how to read market. Below is the latest market report from AFP, my thinking process in purple.

US stocks find strength

May 2, 2009 - 7:47AM

Wall Street stocks wobbled higher overnight as investors digested mixed economic data and braced for the results next week of "stress tests'' on the US banking system. (This opinion is a broadstroke, and is an opinion not an absolute truth. Commentators will try to interpret the market gyrations by attaching reasons to price movements. Not all price movements have logical valid reasons. Sometimes its really just a random walk on Wall Street. There are one hundred and one reasons why investors sell or buy, but we somehow always need to find a logical daily explanantion for why prices move in a certain manner. I would love it if a commentator actually come out and say "I don't know, its random I guess" because in many cases there are really nothing "market moving", prices go up because there are more buyers than sellers, thats all).

The Dow Jones Industrial Average rose 44.29 points (0.5%) to finish at 8212.41. The tech-heavy Nasdaq composite ticked up 1.90 points (0.1%) to 1719.20 and the broad-market Standard & Poor's 500 index rose 4.71 points (0.5%) to 877.52. (This has more relevance as it looks at sections of the markets that moved differently. This is more useful in ascertaining whether there are pockets of strong interest in certain sectors, size of stocks, etc. When the broader index charged up, its a broad based rally, which means everybody is thinking stocks in general are good and is not even discriminating between actual unique fundamentals particular to certain sectors or stocks. Broad based rally indicate "bull market sentiment", the need to buy stocks just to not be left out. If certain sector indices significantly outperforms broader indices, it show a rerating in specific sectors, and may not indicate a bull market trend but rather a rebalancing of exposure to more favourable sectors. It may means that there are particular developments within a specific sector that caused that.)

Economic reports provided conflicting recovery signals on the sick economy now in its 18th month of recession. The troubled manufacturing sector contracted in April for a 15th consecutive month, the Institute of Supply Management said, but the pace of decline was less severe than most analysts projected. (This is good information as it allows me to benchmark where we are in the recession. The average length of a recession is about 16 months and we have gone past that. It also tells me that its worth looking more closely on possible upturn in sentiment and a willingness to be long in equities. If we were in the tenth or eleventh month of a recession, I would probably not be too eager to look at stock investments in general and go for an extended holiday).

The Commerce Department reported factory orders fell by a seasonally adjusted 0.9% in March, in line with expectations after a surprise February increase that had snapped a six-month decline. "The data is still mixed and far from anything solid. While the common theme here is still a contraction, it keeps feeling like a slower contraction,'' said Jon Ogg at 24/7 Wall Street. (Economic data basically tries to confirm what we know. If the bad data is not as bad, it will not move markets immediately. Economic data and trends are like pouring water into a barrel. You need cumulative data to indicate collectively that a certain trend has appeared, e.g. recovering, or not as bad as anticipated, only then will markets be moved by the data. These bits and pieces of economic data needs to be entered into the C drive of our brain and ingested along with other recent economic data for us to form a picture of trend.)

Investors were on tenterhooks waiting for authorities to announce the results of stress tests on the biggest 19 banks that received public bailouts, now expected next Thursday. "The timing of the release of bank stress tests may be giving the market some jitters,'' said Al Goldman at Wachovia Securities. Bank of America dropped 2.6% to $US8.61, JPMorgan Chase shed 1.5% to $US32.49 and Wells Fargo lost 2% to $US19.61. (I have already posted on the likely impact of "stress test" for banks. On the surface it may be seen as negative for those banks being asked to raise capital - but the imposition of the test and its transparency should bolster confidence in the underlying strength of the banks, and may convince more that the worst for banks is coming to an end).

Citigroup, which is trying to raise capital to pay off $US45 billion ($A62.06 billion) in public aid, fell 2.6% to $US2.97 after announcing a deal to sell its Japanese brokerage Nikko Cordial to Japanese megabank Sumitomo Mitsui which was expected to generate $US2.5 billion ($A3.45 billion) in equity.

Among other stocks in focus, Alcoa added a hefty 6.8% to $US9.69. The aluminum producer said it was to sell to Platinum Equity most of its electricity equipment business, which employs about 17,500 people worldwide, for an undisclosed sum.

The market punished firms with earnings reports including credit card company Mastercard, down 5.7% at $US172.90, and insurer MetLife, off 7.7% at $US27.45.

Car stocks were under pressure after dismal April sales reports and Chrysler's appearance at a bankruptcy court hearing in New York a day after filing for Chapter 11 bankruptcy protection.

General Motors skidded 5.7% to $US1.81 and Ford fell 4.8% to $US5.69.

A strong surge in crude prices lifted oil majors. ExxonMobil leapt 2% to $US68.01 and Chevron rose 1.2% to $US66.87 after reporting a better-than-expected profit plunge in the first quarter.

"The earnings news continues to be somewhere between awful and really bad for most companies, but above expectations, which has given Wall Street a lift over the last month,'' Mr Dickson said. (The many corporate actions and earnings announcement should be kept in our C drive as well. Take note on market leaders, results from second and third liners are not as important. These are important in that earnings NEED NOT be rising for a market to turn. Earnings need only be NOT AS BAD as expected for market sentiment to turn).

April produced powerful gains, pushing the Dow up 7.3%, the Nasdaq a hefty 12.3% and the S&P by 9.4%, marking its best month-on-month rally in more than nine years.

The bond market dipped on Friday. The yield on the 10-year US Treasury bond rose to 3.174% from 3.124% on Thursday and that on the 30-year bond advanced to 4.088% from 4.044%. Yields and prices move in opposite directions.

AFP

p/s photo: Son Dam Bi

Upcoming Important Market Catalysts


It seems that the markets have gone into bullish mode. Still, the majority are still very cautious on this run. To me, the bull runs from here on will come in spurts and stop-start as confidence has to trickle back in. What is probable is that we probably would not retests the lows achieved recently but rather finding new levels to build on. Hence we have to be more vigilant to look for short term markets catalysts that can push markets higher or cause a mild correction to set it. Its still a trading market, i.e. more like a 3 steps forward 2 steps back. We should be clear that the markets will not get anywhere close to previous all time highs this year, so bear that in mind. If we can even get back half of the losses i.e. 25%, that would be very decent for this year. For the KLCI, I can see an upper range of 1,050-1,100 being the high range for in 2009. I doubt very much it will break down past 850 again this year, unless something out of the ordinary happens.

To get a better idea of the market's pulse in coming days and weeks, we have to pick out the likely important catalysts. I have already mentioned how the markets started this rally: Pandit's announcement, Geithner's new plan, AIG's generosity etc. The rally was boosted again by an early announcement by Wells Fargo that it made $3bn odd for 1Q2009. The banks dragged the whole market down, their fortunes will again pull the markets up. Hence, Goldman Sachs 1Q earnings to be announced on April 14 is vital, so too will be JP Morgan's on April 16, followed by Morgan Stanley on April21. The first two can be said to be the bigger and more healthy banks running around now. It is crucial that they post decent and positive results. If we take Citigroup and Wells Fargo as examples, it is likely that they will post stellar operating profits. What is more crucial is the amount of write downs - that has to drop significantly in order for the markets to continue its bull run.

Having said that, a very strong run this week may indicate that many are trying to discount the very good earnings of the banks already. Hence it may actually be a sell on news following the earnings. Even so, if the banks showed positive results and little write downs, the correction will be swift and shallow, the run will still be intact.

We also know that Goldman Sachs is raising $5bn as we speak. It is very likely that Goldman will be the first to pay back $10bn to the US government's TARP. That should be greeted as good news as well.

Japan's new additional stimulus is another positive, and the amount of new lending in China has continued to be mind boggling. It is hard to see negatives for the time being. It doesn't mean its safe. Even when the conditions are good, markets will find ways to correct itself by being overbought, but its likely to be 3 steps forward 2 steps back kind of market tango in the upcoming weeks.

p/s photos: Gao Yuan Yuan

Dead Cat Bounce Or Something Livelier?


While many are optimistic over the present short spurt in equity prices, does it really have legs to carry on for at least a few months? The Dow rose nearly 23% in 19 trading days as of last Friday. That was the best performance over 19 days since the Great Depression. The S&P was even better, it rose nearly 25% over that period.

Now, before we get all optimistic, we should remember that there was a very similar rally just a few months back, November 2008 to be precise. In November the S&P 500 rose 21% in just 17 trading days, matching the current stretch closely. We all know what happened after that rally - the markets went to record NEW LOWS even faster.

So, is this another dead cat bounce (its called dead cat bounce, have you ever tried bouncing a dead cat, it does not come back up)? I think there is more credibility to this rally than the November rally.

The November rally was triggered by the wishy-washy announcement that Tim Geithner would be the new Treasury Secretary, and the markets had faith that he would be able to rework new plans to lift the banks of its toxic assets problem. Just as gung-ho in giving Geithner the thumbs-up, the market was even more devastating in selling down the markets when they heard Geithner's actual plans which lacked details and cohesiveness.

So, the November - January period can be characterised in the history book as The Swift Rise & Fall Of Geithner's Credibility.


Since then, Geithner has revealed a more concrete and winnable plan that include professional managers from outside to activate the sale and pricing of toxic assets. Now, the updated plan has more substance and is more convincing, and that was the cornerstone of the rally in March-April. The trigger for the current rally has to be Pandit's Pandora Box, which many thought could only be holding scary items every time he opens it. The surprising announcement that Citigroup made money even in January and February lifted the whole market. Maybe the troubled banks were not that troubled after all.

The feeling was that if these so called near-death banking giants were making money now, that means they are likely to survive, and if they will survive, the markets will NOT be getting another big-time crisis scare ala Bear Stearns / repeated bailouts of AIG / or total nationalisation of these banking giants. When you are able to take these "maybes" out of the equation, its silly not to rally.

Now that we know a bit more about AIG, we also know a bit better why the banks will probably be better off now than say six months ago. Many of the banks were huge beneficiaries when AIG kept taking bailout money. A lot of those funds went straight to the distressed banks which bought Credit Default Swaps on many of the CDOs (which got them into trouble in the first place). The sums owed by AIG to the banks probably was termed as "receivables" in the banks balance sheet, but in reality, the banks really did not know if they were going to get paid. IF AIG was allowed to fail, well, these so called "receivables" would be relegated to write downs. But Geithner and Bernanke knew what AIG was going to do with the money, and swiftly gave AIG the money, even though publicly both were blasting AIG for getting into so much trouble.

Both Geithner and Bernanke allowed AIG to keep scret as to where the bailout funds went, until recently. If they allowed AIG to reveal too soon, it could jeopardise the entire charade as too many could protest AIG's payments and may be stopped halfway, which will trigger a massive jump in counterparty risk. So, for all the hooting and hollering and charade, Geithner and Bernanke did a lot of things behind the curtains to save the global financial markets - and we didn't even write them a thank you note.

The November rally now looked as flimsy as paper as it was mainly riding on the appointment of Geithner, but this rally have more substance. Money went to the banks, CDS were paid out, banks made money, Geithner's new plan has more substance, future potential blind spots were averted smartly ... To add to the mix, we had a decent G-20 meeting which put in place major nations thinking and acting alike.

An even bigger factor was the tweaking of mark to market accounting rule by FASB. This has substantive repercussions, besides allowing the banks more leeway in treating these toxic assets, it will reduce their need to raise capital immediately. More importantly, the new rules will cause a lot more private equity and hedge funds to scramble to bid for these toxic assets as planned by Geithner. The new accounting treatment basically makes buying these assets more appealing.


So, how much legs does the current rally has? For one, I think we have lifted the market bottom to a new threshold. The market is unlikely to revisit 7,000 for the Dow, the new bottom should be 7,700-7,800 which will see many more willing to buy at those levels should it get there again.
Looking at the current rally, the broader S&P 500 had a bigger rally than the Dow, which is to say its not a selective few which are moving the markets but a much broader class. This adds quality to the rally.

p/s photo: Deborah Priya Henry


Markets Are Always Looking For Reasons


Be Smart Buyers Of Stocks

How do you characterise the minor correction, particularly in second and third liners, over the last few days? It is a normal occurrence, especially in a bullish market. I do not trade the market anymore for short term gains (i.e. less than 10 days turnaround).

Whenever you say that you like a stock, there will always be some who will question your integrity the moment it dips. Let's be fair here, an opinion on a stock is just that, an opinion, not a fail-proof trading idea. Certainly not one that will provide for the immaculate in-and-out. Hence when you buy a stock, do not be flustered if the price drops soon after - always ask if the basis, justification and grounds of your purchase are still intact. If they are, everything should even out in the end.

Market rallies such as the one seen on KLSE for the past month needs to be understood further. The leaders of the market for the past one month were second and third liners, that should be easy to spot. That also meant that the beta of these stocks (volatility) are very high. Barring any "bad news", the rally should continue for some time. Markets are always looking for reasons, either to go up, or down. The skill is in spotting what is "reason enough". Bull markets tend to brush away a lot of negative news. Bear markets tend to brush away a lot of good news. Deciding on what will turn the tide - well, like they say, you have pay the tuition fees, man!

When markets run up like it did for the past month - fair and not overly excessive - all participants are looking for reasons to correct. Usually a run will last 1-2 weeks tops, and then correct slightly before moving forward again. Prolonging the bull run will only build up the anticipation of a correction even more, thus making the correction quantum more severe than it needed to be, when it finally arrives.

Discerning between what is "really bad market moving news" - usually they are new news (not the ones that are heard once a week like GDP growth forecasts; or another economist's bearish prediction; or research houses sell recommendations; etc.). They may involve a corporate scandal/ manipulation/ CBT. The bird flu thing which cropped up last week was a good example of largely unanticipated news. I do not think the market's over-reacting here because Asian countries have seen examples of the effect it can have on the real economy should portions of the economy shut down.

Markets are necessarily a discounting instrument. It tries to discount all the realistic projections, net present values, etc... as best it could. If the market really thinks that Malaysia's GDP would grow by 8% in 2008 - the stock market would move up to try and discount that properly. In general, the stock market cannot look too far ahead, 12-18 months is about as far as it will go as studies have shown that markets seem to regard anything longer than that as too wishy-washy to take into account properly (i.e. too many variables and things can happen to change the equation).

I have stated that I am bullish for Asian stocks this year, and I have not seen anything that would derail that, with the exception of a full blown bird flu epidemic.